
Market Headline: Private Credit Takes the Asset-Based Pivot in Early 2026
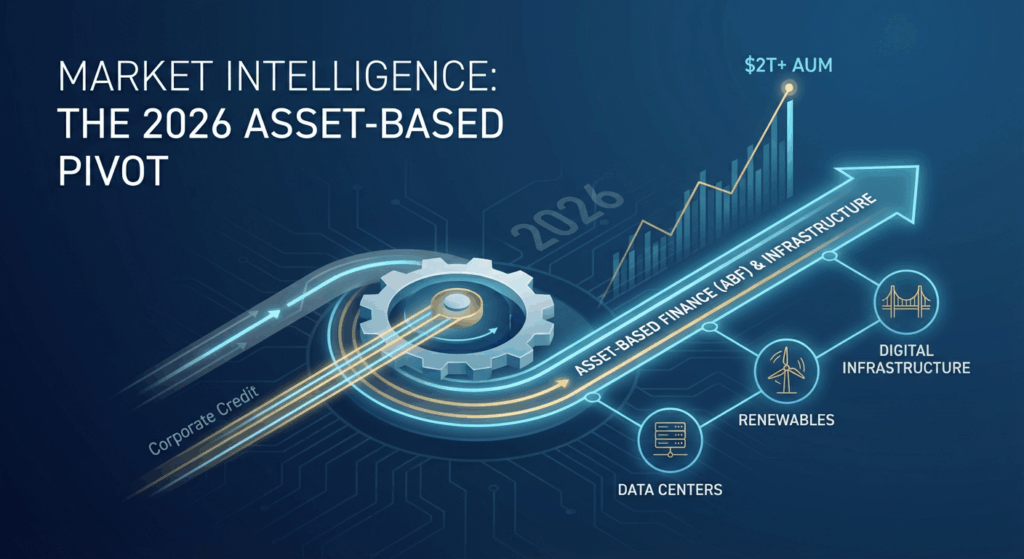
As of late January 2026, the private credit market is executing a structural pivot. While the “golden age” of direct lending stabilized borrowing costs for middle-market corporates, the search for yield and scale is driving capital aggressively toward Asset-Based Finance (ABF) and infrastructure debt. According to Moody’s 2026 Outlook, the asset class is on track to exceed $2 trillion in AUM this year, fueled not just by traditional corporate lending, but by a surge in partnerships to fund diverse asset pools ranging from consumer loans to data centers.
The narrative for Q1 2026 is defined by complexity over vanilla credit. As traditional M&A and leveraged buyout (LBO) activity begins to escalate, competition among lenders is compressing yields in standard direct lending, pushing managers to innovate with hybrid structures and NAV lending to deploy capital.
Quantitative Snapshot: The Data Landscape
The following metrics highlight the tightening competitive landscape and the massive scale of capital deployment leading into 2026.
| Metric | Current Status / Value | Trend / Comparison | Source |
|---|---|---|---|
| Private Credit AUM | > $2.0 Trillion (2026 proj.) | Accelerating toward $4T by 2030 | Moody’s |
| ABF Spreads | Tightening | Compressed 10-30 bps in late ’25 | MetLife IM |
| Deal Volume (Sample) | $11.5B (MetLife Q3 Origin.) | Bilateral & club deals driving flow | MetLife IM |
| Infrastructure Capital | High Demand | Driven by digital infra & renewables | MetLife IM |
Sector Analysis: Where Capital is Flowing
Hot: Asset-Based Finance (ABF) & Infrastructure
The most significant rotation is out of general corporate cash-flow lending and into assets backed by collateral. Moody’s notes that ABF is becoming a “core part” of funding growth, with managers stepping in where banks remain constrained. Specifically, digital infrastructure (data centers) and renewable energy projects are absorbing billions in capacity, supported by long-dated issuance and stable credit fundamentals.
Steady: Corporate Private Placements
Despite the shift to ABF, corporate private placements remain active. Institutional demand for long-duration assets fueled oversubscription in late 2025, with premiums over public benchmarks sustaining investor interest. However, Nuveen observes that the market is “maturing,” requiring more sophisticated analysis to discern quality in a crowded field.
Scanning for Risk: Valuation Transparency
Regulatory scrutiny is intensifying. Following enforcement actions in 2025 related to disclosures, the SEC is placing stricter emphasis on valuation transparency for illiquid assets. AInvest highlights that as retail participation grows, ensuring consistent third-party valuations (Rule 2a-5) is becoming a critical compliance hurdle for fund managers.
Implications
For Borrowers:
The “menu” of financing options has expanded. Borrowers with hard assets (receivables, equipment, infrastructure) found in the ABF market can command competitive pricing as lenders compete for collateral-backed safety. Middle-market firms looking for LBO financing will find a receptive audience but should expect tighter covenants or lower leverage multiples as lenders navigate a “maturing” cycle.
For Lenders & Investors:
The easy beta trade is over. MetLife’s data showing spread compression in ABF signals that alpha will increasingly come from origination partnerships and operational complexity rather than simple credit spreads. Furthermore, the rising interconnectivity between private credit funds and traditional banks poses new contagion risks that require rigorous stress testing.
Key Market Insights
- Volume Velocity: Private credit AUM is projected to break $2 trillion in 2026; the market is too large to ignore.
- Spread Compression: Competition in Asset-Based Finance is tightening spreads (10-30 bps recent contraction), benefiting borrowers.
- Sector Rotation: Capital is rotating heavily into digital infrastructure and consumer loan pools (ABF) as corporate lending saturates.
- Regulatory Watch: Valuation transparency is the top regulatory risk; expect stricter enforcement on fair value methodologies.
- Retail Influx: The “democratization” of private credit continues, with wealth channels becoming a primary source of new dry powder.


