
The Financing Challenge: Speed vs. Cost
In the current 2026 leveraged finance landscape, the boundary between the broadly syndicated loan (BSL) market and private credit continues to blur, yet the fundamental trade-off for operators remains: speed and certainty versus cost of capital. For middle-market sponsors seeking to close buyouts specifically in the $100M to $500M enterprise value range, the unitranche facility has cemented itself not merely as an alternative, but as the default baseline structure.
With global private credit assets under management crossing the $2 trillion mark recently, the depth of capital available for these structures has enabled “jumbo unitranches” to rival public market execution. However, the appeal is not just size; it is structural simplicity. In a volatile rate environment, the ability to lock in a single facility without rating agencies, roadshows, or “market flex” provisions allows sponsors to pay a premium, typically 50 to 100 basis points, in exchange for execution certainty. This article dissects the mechanics of the unitranche vehicle, revealing how lenders engineer yield behind the scenes and how borrowers can negotiate better terms in the current vintage.
Structure Breakdown: The “One-Doc” Solution
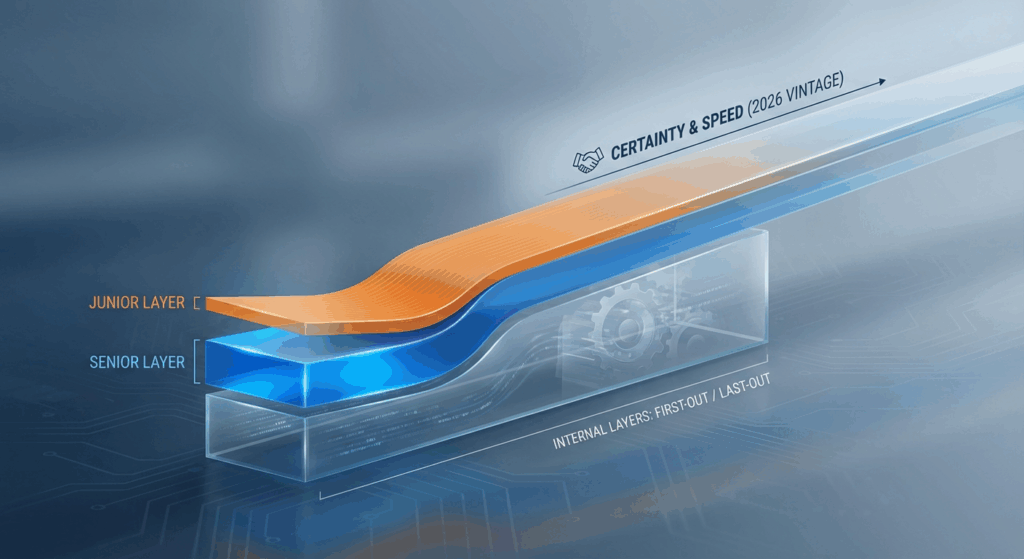
A unitranche facility combines senior debt and subordinated (junior/mezzanine) debt into a single instrument with one interest rate, one amortization schedule, and one set of loan documents. To the borrower, the structure appears monolithic. Behind the scenes, however, lenders often bifurcate the risk through an Agreement Among Lenders (AAL).
The Mechanics: First-Out / Last-Out
While the borrower pays a blended rate, the lenders may split the loan into:
- First-Out Tranche: Often held by a bank or low-cost capital provider. This tranche has payment priority and receives a lower yield (e.g., SOFR + 300).
- Last-Out Tranche: Held by the private credit fund. This tranche is subordinate in payment priority and effectively acts as the mezzanine layer, capturing a significantly higher yield (e.g., SOFR + 800) to subsidize the blend.
Hypothetical Deal Profile
Consider a $100M Enterprise Value B2B software buyout requiring $50M in debt financing (5.0x leverage on $10M EBITDA).
- Facility Size: $50M Unitranche Term Loan.
- Interest Rate: SOFR + 575 bps (Blended).
- OID (Original Issue Discount): 98.0 (2% upfront fee).
- Amortization: 1% per annum (minimal required principal payments).
- Tenor: 6 years.
- Covenants: Single maintenance covenant (e.g., Total Net Leverage not to exceed 6.5x), significantly looser than traditional bank loans.
In this structure, the “speed premium” is real. Sources indicate that unitranche executions can close 30 to 45 days faster than syndicated alternatives, saving the deal from market volatility risk [privateequitybro.com].
How It Compares: Unitranche vs. Senior/Mezz Stack
The primary alternative to a unitranche is a traditional bifurcated capital stack involving a senior bank loan paired with mezzanine debt or second lien notes. Here is the structural trade-off:
1. Intercreditor Complexity
Senior/Mezz: Requires a complex Intercreditor Agreement (ICA) between two distinct creditor classes. In a bankruptcy, this public conflict can stall restructuring.
Unitranche: Uses a private AAL. The borrower has a single counterparty for amendments and waivers. This “bilateral” relationship is crucial during periods of underperformance, allowing for faster workouts without a lender syndicate voting block [fe.training].
2. Cost vs. Flexibility
Senior/Mezz: Often carries a lower weighted average cost of capital (WACC) if the senior portion is maximized at low bank rates. However, bank senior debt comes with strict maintenance covenants (quarterly tests) and amortization pressure.
Unitranche: More expensive on the headline rate (blended), but typically offers “covenant-lite” or “covenant-loose” terms similar to the high-yield bond market, providing the operator more breathing room to execute growth strategies [joinarc.com].
Current Market Terms (2026 Vintage)
As of early 2026, the unitranche market has stabilized following the rate hikes of the previous cycle. Standard terms for sponsor-backed middle-market assets currently include:
- All-in Yields: 11.5% – 13.0% for average credit profiles. Lenders are focusing on total return, often utilizing SOFR floors of 3-4% [privateequitybro.com].
- Leverage Profiles: Total leverage hovers around 4.75x – 5.50x EBITDA. Lenders have pulled back from the >6x peaks seen in 2021, focusing now on fixed charge coverage ratios and free cash flow visibility.
- Portability: While rare in 2023-2024, portability clauses (allowing the debt to stay in place if the company is sold) have started reappearing in top-tier credits to incentivize sponsors.
- Call Protection: Lenders demand protection for their yield. Standard structure is 103 / 102 / 101 (3% penalty if refinanced in Year 1, 2% in Year 2, etc.), ensuring a minimum return on capital deployment.
Structuring Guidance for Operators & Investors
For Borrowers (Sponsors/Operators)
When negotiating a unitranche, focus capital on defining EBITDA add-backs. Since the maintenance covenant is often leverage-based, the “Adjusted EBITDA” definition is your primary shield against default. Additionally, negotiate the “incremental facility” (accordion feature) upfront. This allows you to raise additional debt for add-on acquisitions under the same document without re-pricing the entire facility, a key tool for buy-and-build strategies [lexology.com].
For Investors
Scrutinize the AAL if participating in a syndicated unitranche. If you are in the “Last-Out” position, ensure you have consent rights over material changes, specifically regarding the release of collateral or extension of maturity dates. The risk in unitranche is often that the “First-Out” controlling lender may make decisions in a workout that protect their principal while eroding the cushion for the Last-Out holders.
Key Deals Takeaways
- Certainty Premium: Borrowers pay ~50-100 bps more for unitranche to avoid syndication risk and market flex clauses.
- Structural Opacity: The AAL creates a “virtual” senior/subordinated structure visible only to lenders, offering a seamless interface for the borrower.
- Covenant Design: Leverage maintenance covenants are standard, but the definition of EBITDA is the true battleground for headroom.
- Prepayment Penalties: Expect hefty call protection (103/102/101) as private credit funds need to lock in yield duration.
- Scale: The $1B+ “Jumbo Unitranche” is now a viable alternative to the BSL market for large-cap issuers.


