
The Setup: A High-Stakes Tech Bet
In the world of leveraged finance, few stories illustrate the double-edged sword of debt as clearly as the 2024 restructuring of Pluralsight. For founders and operators exploring capital options today in 2026, looking back at this transaction provides a masterclass in how capital structure dictates control.
In 2021, at the height of the software valuation boom, Vista Equity Partners took the workforce development platform Pluralsight private in a deal valued at approximately $3.5 billion. The thesis was a classic private equity playbook: acquire a high-growth asset, apply operational improvements, and exit at a higher multiple. To fund the transaction, significant leverage was employed, based on the assumption that robust recurring revenue would service the debt while the equity value compounded.
The Turn: When Macro Meets Micro
However, the macroeconomic tide turned shortly after the ink dried. Interest rates began their historic climb, and the “growth at all costs” era of SaaS valuations came to an abrupt halt. Suddenly, the debt service burden—which appeared manageable in a near-zero interest rate environment—became a suffocating weight on the company’s cash flows.
By 2024, Pluralsight found itself in a precarious position. The company generated cash, but arguably not enough to support its capital structure under the new rate regime. In an attempt to preserve equity value, the sponsor reportedly explored aggressive liability management exercises (LMEs), including moving intellectual property into unrestricted subsidiaries to raise fresh capital—a tactic often referred to as a “drop-down.”
The Outcome: The Lenders Take the Keys
This is where the story pivots from a standard struggle to a defining moment for private credit. The lenders, a group led by Blue Owl Capital, did not sit idly by. Unlike the dispersed bank syndicates of the past who might have amended and extended terms to avoid ownership, these private credit funds had the mandate and capability to operate the asset.
According to reports from restructuringnewsletter.com and bnnbloomberg.ca, the conflict culminated in a comprehensive restructuring in mid-2024. The lenders agreed to inject new capital and reduce the debt load, but the cost was absolute: the original equity was effectively wiped out. The lender group emerged owning roughly 85-100% of the company.
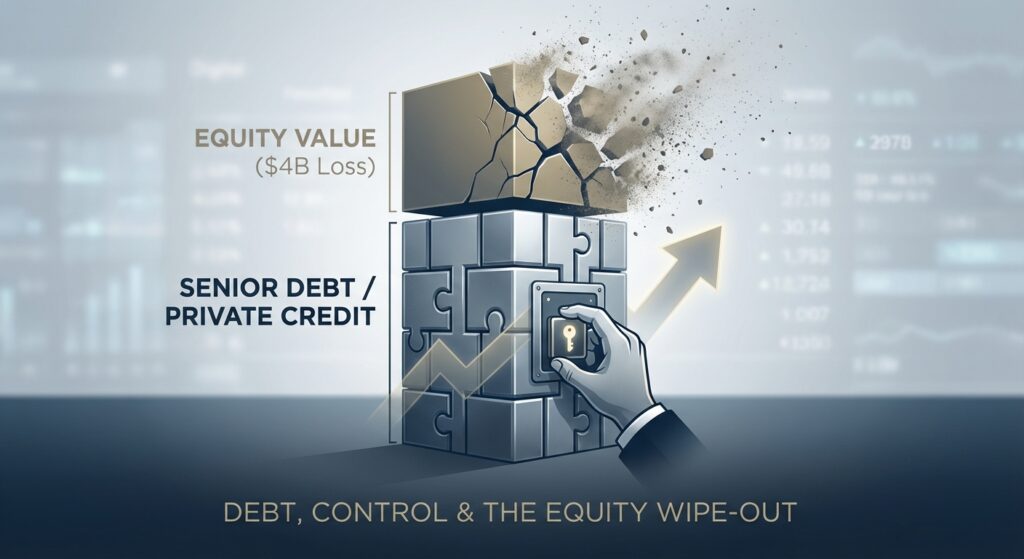
The result was a stark transfer of value. Vista and its co-investors reportedly wrote off nearly $4 billion in equity value, while the lenders converted their distressed debt into controlling equity, positioning themselves to capture future upside.
The Lessons: Understanding Capital Seniority
For founders and CFOs, the Pluralsight saga is not just a Wall Street drama; it is a fundamental lesson in the mechanics of leverage.
1. Debt is senior for a reason.
In good times, equity gets the glory. In hard times, debt gets the company. The “absolute priority rule” isn’t just a bankruptcy concept; it is the gravity of finance. If a capital structure becomes unsustainable, the fulcrum security—the debt layer where value runs out—becomes the new ownership class.
2. Private Credit is active, not passive.
The era of “dumb money” debt is over. Today’s private credit firms are sophisticated operators. As seen with Blue Owl, they are willing and able to take the keys if covenants are breached or if the capital structure needs a reset. Borrowers should view their lenders as potential future partners (or owners), not just utility providers.
3. Valuation discipline matters.
Leverage acts as a multiplier. When asset values drop, high leverage wipes out equity distinctively fast. Pluralsight’s fundamentals were not necessarily broken, but its capital structure was mismatched with the new valuation reality.
Key Insights
- Control follows the fulcrum: Ownership belongs to the most senior creditor not covered by the enterprise value.
- Covenants exist to force the conversation: They are the trigger points that allow lenders to step in before value completely evaporates.
- Lender composition matters: A concentrated group of fierce private credit lenders behaves differently than a dispersed syndicate of commercial banks.
- Equity is an option on the future: If the debt burden consumes all current cash flow, the equity option can expire worthless, regardless of the brand value or revenue scale.
- Restructuring is a reset: For the operating company, this was a new beginning with a cleaner balance sheet, proving that a good business can survive a bad capital structure—even if the original owners do not.


