
The Underwriting Question That Determines Long-Term Returns
Before any term sheet is signed, every serious credit professional should be able to answer one foundational question: If this borrower defaults eighteen months from now, how much do we recover — and why?
That question is not pessimism. It is the engine of rigorous underwriting. Spreads are visible and easy to compare. Recovery value is opaque, asset-specific, and almost never priced correctly by lenders who chase yield without first stress-testing collateral. As institutional credit manager OHA has noted in its Credit Investor’s Checklist, two portfolios with identical spreads and default rates can produce realized returns that differ by 44% simply because of their divergent recovery profiles. When defaults rise and recovery rates fall simultaneously — as they reliably do in stressed markets — lenders who skipped this step absorb compounded losses.
This article presents a practitioner’s framework for collateral assessment and recovery analysis: the metrics to model, the calculations to run, the red flags to catch, and the checklist every underwriter should complete before a credit committee vote.
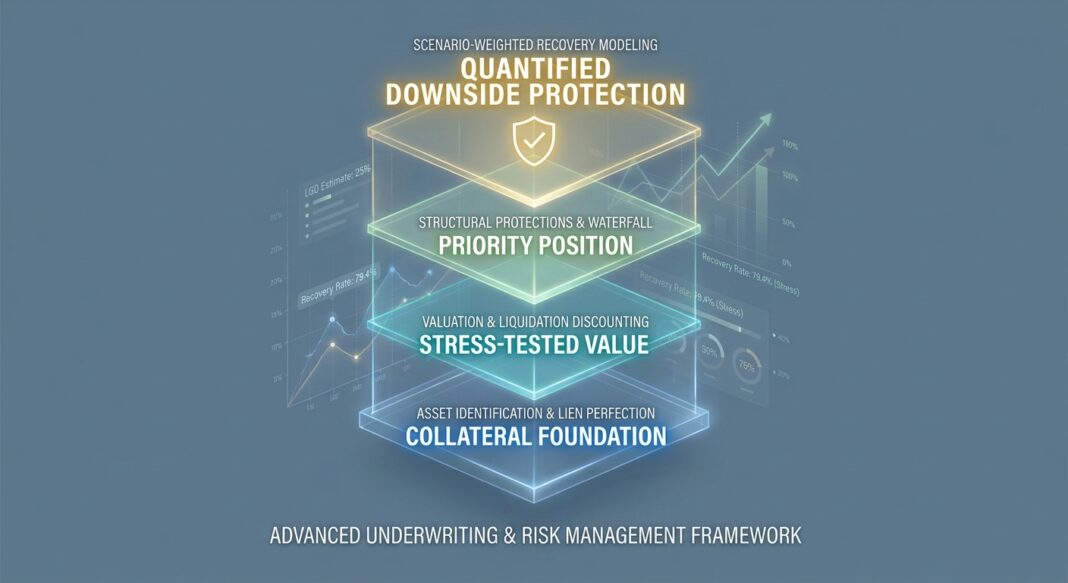
The Analytical Framework: Collateral Assessment in Four Layers
Effective collateral assessment is not a single calculation — it is a layered methodology that moves from asset identification to scenario-weighted recovery value. The framework draws on structured finance principles formalized by agencies including Scope Ratings, which requires analysis of collateral risk, structural risk, and counterparty risk as integrated components of any credit opinion.
Layer 1 — Asset Identification and Lien Perfection
Begin by cataloguing every pledged asset: accounts receivable, inventory, equipment, real property, intellectual property, and equity pledges in subsidiaries. Confirm lien perfection through UCC filings, title searches, and inter-creditor agreements. An unperfected lien is not collateral — it is an illusion.
Layer 2 — Valuation and Liquidation Discounting
Assign each asset class a liquidation value haircut based on orderly versus distressed sale assumptions. Enterprise value collateral — common in sponsor-backed transactions — requires a separate EV-to-EBITDA bridge under stress conditions. Equipment and real property should be valued by third-party appraisers, with forced-liquidation discounts applied (typically 30–60% of appraised value depending on asset type and market depth).
Layer 3 — Structural Protections and Priority Waterfall
Map the capital structure waterfall. Identify where your instrument sits relative to revolving credit facilities, senior secured term loans, second-lien debt, mezzanine, and equity. The PGIM Large Cap Private Credit framework highlights that tighter security documentation and structural seniority have historically produced lower defaults and higher recovery rates in large-cap transactions — a direct function of where you sit in the waterfall.
Layer 4 — Scenario-Weighted Recovery Modeling
Run at least three recovery scenarios — base, stress, and severe stress — weighted by assigned probabilities. The output is an expected recovery rate expressed as a percentage of outstanding principal. This figure, combined with your probability of default, produces your Loss Given Default (LGD) estimate, which drives economic capital requirements.
Walking Through the Calculations: A $10M EBITDA Manufacturing Borrower
Consider a sponsor-backed manufacturing company with $10M in trailing twelve-month EBITDA, $55M in senior secured term loan debt (5.5x leverage), and a collateral package consisting of equipment ($18M appraised), receivables ($6M eligible borrowing base), and enterprise value.
Step 1 — Forced Liquidation Value of Hard Assets
Apply a 45% liquidation discount to equipment: $18M × 0.55 = $9.9M. Apply an 80% advance rate to eligible receivables: $6M × 0.80 = $4.8M. Hard asset recovery pool: $14.7M before senior costs.
Step 2 — Stress-Case Enterprise Value
Under a stress scenario, assume EBITDA contracts 30% to $7M. Apply a distressed EV multiple of 5.0x (versus the original underwriting multiple of 8.0x). Stress EV = $35M. After deducting a revolving credit facility balance of $5M and transaction costs of ~3%, net EV available to term loan holders = $28.95M.
Step 3 — Blended Recovery Estimate
Total recovery pool (hard assets + EV): $14.7M + $28.95M = $43.65M against $55M of term loan principal. Blended stress-case recovery rate = 79.4%. This is your LGD anchor. Under a severe stress scenario (EBITDA down 50%, EV multiple compresses to 4.0x), recovery falls to roughly 52–58% — a meaningful difference that should inform pricing and structural protections.
Probability of Default and Expected Loss
Using the credit analysis framework taught by the CFA Institute, expected loss is the product of Probability of Default (PD), Loss Given Default (LGD), and Exposure at Default (EAD). At a 5% PD, 25% LGD (stress case), and $55M EAD: Expected Loss = 0.05 × 0.25 × $55M = $687,500 annually. This becomes the minimum spread hurdle above the risk-free rate before any return on capital is generated.
What Institutional Lenders Look For — and Where Underwriters Fail
Experienced credit managers evaluate collateral quality not just at origination but continuously throughout the loan life. The OHA Credit Investor’s Checklist stresses that managers should re-underwrite portfolio positions continuously and challenge prior assumptions — a discipline that requires real-time collateral monitoring, not point-in-time snapshots.
Portfolio-level risk quantification tools, including Moody’s Analytics RiskFrontier, are designed specifically to calculate each instrument’s marginal contribution to portfolio risk, set concentration limits, and stress-test capital requirements across scenarios. These platforms operationalize what skilled underwriters do manually: translate individual collateral assessments into portfolio-level expected loss and capital adequacy metrics.
Common Mistakes and Red Flags
- EBITDA add-back inflation: Loose EBITDA definitions — a tactic flagged in connection with deals like J. Crew, Pluralsight, and Serta — can artificially suppress reported leverage, overstating coverage and understating true LGD. Always stress-test normalized EBITDA before applying any EV multiple.
- Unperfected or shared collateral: Inter-creditor agreements that permit asset transfers or collateral stripping (the “J. Crew trap”) can render a senior lien effectively subordinated without formal reclassification.
- Overreliance on EV collateral: Enterprise value is cyclical, management-dependent, and illiquid. Hard asset coverage provides a more reliable floor in distress scenarios.
- Static collateral models: A borrowing base calculated at close may deteriorate significantly within twelve months if receivables age or inventory turns slow. Build in quarterly field exams and springing triggers.
- Ignoring liability management risk: Out-of-court restructurings and liability management exercises (LMEs) can subordinate existing lenders without default — making documentation quality a direct input to recovery modeling.
📊 Credit Performance Reference Points
- Recovery rates for senior secured loans in distressed cycles have historically ranged from approximately 55–75%, versus 30–45% for unsecured bonds, underscoring the structural value of seniority and perfected collateral.
- Portfolios with higher recovery profiles can generate realized spreads up to 44% higher than lower-recovery portfolios with identical nominal spreads and default rates, per OHA’s illustrative analysis.
- Large-cap private credit transactions — characterized by tighter documentation and greater structural seniority — have historically exhibited lower default incidence and higher recoveries relative to broadly syndicated equivalents, as documented by PGIM.
- Credit spread curves tend to widen and steepen during periods of weak economic activity, per the CFA Institute credit analysis framework — the precise environment in which collateral quality is most scrutinized and recovery assumptions are tested.
Collateral Assessment Underwriting Checklist
Before advancing any credit to committee, a disciplined underwriter should be able to confirm each of the following:
- Asset Schedule Verified: Has a complete schedule of pledged assets been obtained and cross-referenced against the security agreement?
- Lien Perfection Confirmed: Have UCC-1 financing statements been filed in the correct jurisdictions? Are priority positions confirmed relative to all other secured creditors?
- Third-Party Appraisals Ordered: For equipment and real property, has an independent appraisal been completed within the last six months? Does it include both orderly and forced-liquidation scenarios?
- Borrowing Base Stress-Tested: Has the eligible receivables pool been aged and haircut? What is the borrowing base value under a 90-day collection cycle?
- EV Multiple Justified: Is the underwriting EV multiple supportable against comparable transactions? What does EV imply under a 30% and 50% EBITDA compression?
- EBITDA Normalized: Have all management add-backs been reviewed and challenged? Is run-rate EBITDA defensible over a 12-month forward view?
- Inter-Creditor Agreement Reviewed: Does any senior facility contain provisions that could subordinate your position or facilitate collateral transfers?
- LME Protections Assessed: Does the credit agreement contain anti-priming protections, consent requirements for asset transfers, and restricted payments covenants?
- Recovery Scenarios Modeled: Are base, stress, and severe stress recovery rates documented with probability weights and LGD estimates?
- Monitoring Triggers Set: Are financial maintenance covenants, borrowing base reporting requirements, and collateral field exam schedules included in the credit agreement?
Key Takeaways
- 🔑 Recovery rates, not spreads, drive realized returns. Two portfolios with identical spreads can produce dramatically different outcomes based solely on recovery rate differentials — making collateral quality a primary, not secondary, underwriting input.
- 🔑 Layer your collateral analysis. Hard asset liquidation values, enterprise value stress cases, and structural waterfall position must all be modeled independently and then combined into a scenario-weighted recovery estimate.
- 🔑 Documentation quality is a collateral input. Loose EBITDA definitions, permissive asset transfer baskets, and weak anti-priming protections directly reduce the practical value of pledged collateral in a restructuring — regardless of what the appraisal says.
- 🔑 Re-underwrite continuously. Collateral values are dynamic. Receivables age, inventory obsoletes, and enterprise value compresses with market cycles. Static collateral models embedded at origination become unreliable guides as borrower conditions evolve.
- 🔑 Model your expected loss, not just your yield. Anchor every investment in a formal PD × LGD × EAD framework. The expected loss figure is the minimum spread hurdle — anything below it means the lender is not being compensated for the credit risk being underwritten.


