
Underwriting & Risk Management | Bond Capital
EBITDA Adjustments and Normalization in Credit Underwriting: A Lender’s Discipline Framework
Published September 28, 2026
The Underwriting Challenge: When Adjusted EBITDA Obscures True Debt Capacity
A sponsor brings you a deal. The borrower — a $10M revenue manufacturing company — reports $2.4M in Adjusted EBITDA. The ask is a $8.4M senior term loan, which the sponsor presents as a clean 3.5x leverage credit. It looks workable. Then you open the adjustment schedule.
You find $500,000 in add-backs: $150K labeled “non-recurring” legal fees that have appeared for three consecutive years, $200K of stock-based compensation the sponsor insists is non-cash, and $150K of projected cost savings from a procurement initiative that hasn’t been implemented yet. None of it is fabricated — but none of it is defensible either.
Strip those items out, and lender-adjusted EBITDA falls to $1.9M. Leverage moves to 4.4x. Your debt service coverage ratio compresses from a comfortable 1.8x to a covenant-tight 1.3x. The deal structure, pricing, and approval calculus all shift — because the earnings base shifted.
This scenario plays out across middle-market lending desks every week. EBITDA normalization is not a valuation formality — it is the foundational underwriting act. Getting it wrong means underwriting to a fiction. Getting it right protects principal, informs covenant design, and builds a credit relationship anchored in actual cash flow.
The Framework: Three Versions of EBITDA Every Lender Must Distinguish
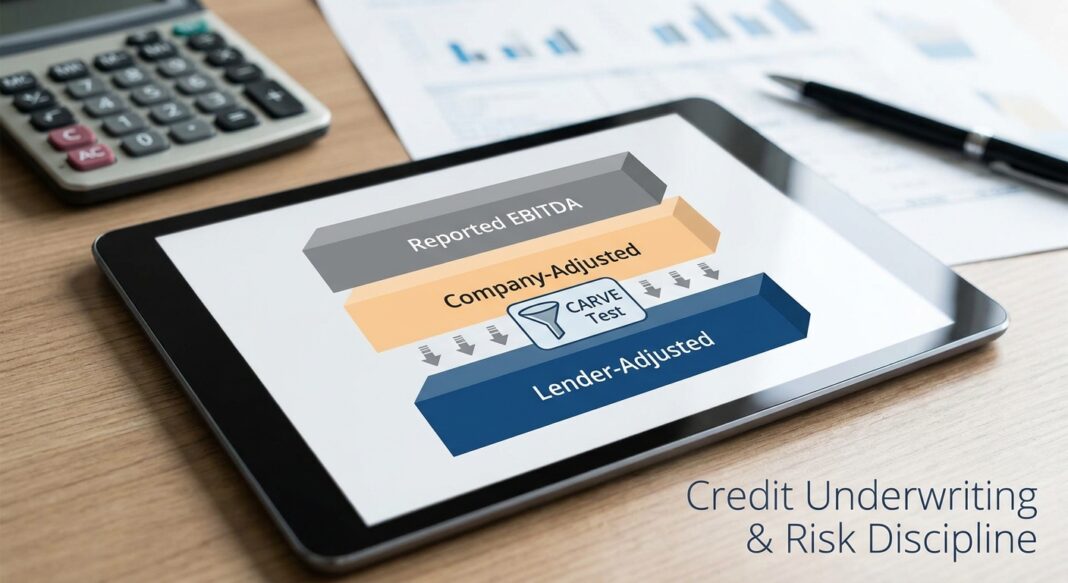
Before applying any adjustment, a disciplined credit officer must recognize that EBITDA is not a single number — it exists in at least three distinct forms, each with a different purpose and risk profile.
The EBITDA Stack
| Version | Source | Risk to Lender |
|---|---|---|
| Reported EBITDA | GAAP financial statements | May miss legitimate normalizations |
| Company-Adjusted EBITDA | Management / sponsor schedule | Often includes unsupported add-backs |
| Lender-Adjusted EBITDA | Underwriter’s independent review | The only version that should govern covenants |
As practitioners at Crediflow AI’s credit analysis desk note, “lender-adjusted EBITDA reflects what the underwriter accepts after review” — and critically, “covenant-defined EBITDA may follow a separate formula in the credit agreement, which can differ from what a credit officer uses for underwriting.” That divergence creates structural risk if not explicitly reconciled at origination.
The analytical goal is clear: EBITDA adjustments are add-backs or deductions used to estimate normalized, recurring cash earnings available for debt repayment. In credit analysis, the objective is never to maximize earnings — it is to measure the borrower’s realistic capacity to service debt under a sustainable operating base.
The Measurement Period Matters
Most lenders anchor to LTM (Last Twelve Months) EBITDA as the base period. Run-rate EBITDA — which projects forward from current conditions — requires a higher evidentiary bar. Any run-rate adjustment must be supported by signed contracts, implemented price changes with customer retention data, or operational changes already reflected in trailing results. Anticipated cost savings that depend on post-closing actions should be rejected or heavily discounted.
Example: Analyzing a $10M EBITDA Manufacturing Company
Consider a middle-market industrial distributor with reported LTM EBITDA of $4.25M. The sponsor presents an adjusted figure of $4.9M, using a standard add-back schedule. The lender’s job is to reconstruct that number from the bottom up:
- Reported EBITDA: $4.25M
- Add: One-time restructuring charge (documented, non-recurring): +$200K ✓
- Add: Owner compensation above market replacement cost: +$175K ✓ (with comp benchmark support)
- Reject: Projected logistics savings (not yet implemented): –$150K ✗
- Reject: Legal fees labeled “non-recurring” (three-year pattern): –$125K ✗
- Lender-Adjusted EBITDA: $4.475M
At an 8.0x multiple, the $425K gap in accepted adjustments represents over $3.4M in enterprise value — and directly determines how much debt this business can support.
The Analysis: Applying the CARVE Test and Stress-Testing Coverage
The CARVE Test for Every Add-Back
A practical and repeatable framework for evaluating any EBITDA adjustment is the CARVE test, which disciplines underwriters to ask five sequential questions about each proposed add-back:
CARVE Test — Add-Back Evaluation Framework
- C — Cash: Did this item actually use cash, and will similar cash outflows continue? A non-cash accounting charge may pass; a recurring consulting fee likely will not.
- A — Auditable: Does the adjustment have objective evidence — not just a borrower narrative or broker memo? Require GL detail, invoices, or board resolutions.
- R — Recurring: Review at least 24–36 months of history. If a “non-recurring” cost appears in every period, it is recurring by definition.
- V — Verifiable: Does the number connect to GL detail, bank activity, tax filings, or independent third-party documents?
- E — Excluded-from-Operations: Is this cost necessary to generate revenue, serve customers, maintain compliance, or preserve the asset base? If yes, it stays in EBITDA.
Leverage and Coverage: Running the Math
Once lender-adjusted EBITDA is established, the underwriter calculates the core credit metrics that drive approval, structure, and pricing:
- Total Leverage: Total Debt ÷ Lender-Adjusted EBITDA — lenders typically cap covenant leverage at 3.0x–4.5x, and flag anything above 6.0x as distressed territory.
- Senior Leverage: Senior Debt ÷ EBITDA — isolates first-lien exposure.
- DSCR (Debt Service Coverage Ratio): (EBITDA – CapEx – Taxes) ÷ (Interest + Required Amortization) — a DSCR below 1.0x means operations cannot cover debt service; most institutional lenders require a minimum 1.20x–1.25x floor.
- Fixed Charge Coverage Ratio (FCCR): Expands DSCR to include lease obligations and other fixed charges.
Stress Test: What Happens at Stressed EBITDA?
Institutional lenders do not underwrite to base case only. A standard stress test applies a 20–30% EBITDA haircut to simulate a revenue contraction, margin compression, or customer concentration event. If lender-adjusted EBITDA is $4.475M and falls 25% to $3.36M, a $13M term loan moves from 2.9x leverage to 3.9x — potentially outside policy. That stress test output informs covenant set-points, equity cushion requirements, and whether the sponsor needs to bring more equity to the table.
Industry Standards: What the Credit Markets Are Telling Underwriters Right Now
The 2025–2026 credit environment has produced a meaningful tightening of EBITDA adjustment discipline. Lenders who relaxed add-back standards during the 2020–2021 liquidity cycle are now managing the consequences in their portfolios.
Credit Market Data Box — 2025–2026
- 📊 Leveraged loan default rates reached approximately 7.5% projected year-end 2025, nearly double the 3.4% long-run historical average — per Moody’s Credit Strategy U.S. Outlook (July 2025).
- 📊 High-yield bond default rates were projected at 3.2% for calendar 2025, rising above 4% by Q1 2026, per Moody’s — still below the 4.5% historical average but trending higher.
- 📊 Recovery rates for defaulted leveraged loans tracked near 60% (Moody’s, 2025), implying annual losses of approximately 2.8% — but the explosion of Liability Management Exercises (LMEs) has complicated recovery measurement significantly.
- 📊 Distressed exchanges accounted for approximately 56% of all defaults through 2025, reflecting the prevalence of out-of-court restructurings over traditional bankruptcies.
- 📊 18% of post-closing M&A disputes traced to disagreements over EBITDA adjustment definitions in purchase agreements, per the 2025 SRS Acquiom Buy-Side R&W Insurance Claims Study — underscoring that EBITDA definition disputes extend well past closing.
- 📊 QoE is now mandatory: Under SBA SOP 50 10 8.1, effective October 1, 2026, independent Quality of Earnings reports are required for all SBA 7(a) acquisition loans with purchase prices of $3M or more — a formal regulatory acknowledgment that lender reliance on unverified management-adjusted EBITDA creates systemic credit risk.
Common Red Flags in EBITDA Adjustment Schedules
Experienced credit officers learn to pattern-match on the add-back categories most likely to mask deteriorating credit quality:
- Recurring “Non-Recurring” Items: If legal fees, restructuring charges, or “one-time” severance appear in every trailing period, they are structural costs — not adjustable.
- Unimplemented Cost Savings: Add-backs for synergies or savings that depend on post-closing actions are forecasts, not facts. Lenders should accept these only partially — or not at all — until results appear in trailing financials.
- Stock-Based Compensation: The market has shifted sharply here. Sponsor LOIs in the lower middle market routinely excluded all SBC add-backs in 2025–2026, reversing what was standard practice in 2021.
- Sudden Margin Expansion: A rapid improvement in gross or EBITDA margins without an identifiable operational change is a classic yellow flag — it may reflect inventory costing adjustments, freight capitalization changes, or warranty reserve releases rather than genuine earnings power.
- Related-Party Rent and Compensation: Below-market rent paid to a related party inflates EBITDA artificially. The underwriter must normalize these to market rates — which may reduce, not increase, the adjusted figure.
- The Add-Back Inflation Trap: Consider the math: a borrower presenting $2.4M adjusted EBITDA with $500K of unsupported add-backs is actually a $1.9M EBITDA credit. At 3.5x requested leverage, that moves the actual leverage to 4.4x — which can change pricing, structure, covenant architecture, and approval authority.
Underwriting Checklist: EBITDA Normalization Diligence Protocol
The following step-by-step checklist represents institutional best practice for any lender conducting EBITDA normalization as part of a credit underwriting review.
Phase 1 — Document Collection
- ☐ Three years of audited or reviewed financial statements (P&L, balance sheet, cash flow)
- ☐ Three years of federal tax returns + IRS transcript confirmation
- ☐ Month-by-month general ledger detail for the LTM period
- ☐ Management-prepared adjustment schedule with line-item narrative
- ☐ Owner/officer compensation documentation vs. market benchmarks
- ☐ Copies of all leases, related-party agreements, and management fee arrangements
- ☐ Any existing QoE report (sell-side or independent); if absent for a $3M+ transaction, commission one
Phase 2 — EBITDA Reconstruction
- ☐ Start from GAAP-reported EBITDA — never start from management’s adjusted number
- ☐ Apply CARVE test to each proposed add-back (Cash / Auditable / Recurring / Verifiable / Excluded-from-operations)
- ☐ Normalize owner compensation to market replacement cost (upward or downward)
- ☐ Normalize related-party transactions to market economics
- ☐ Reject unimplemented cost savings; accept implemented savings only if documented in run-rate results
- ☐ Build both LTM and 2-year average EBITDA for cyclicality context
- ☐ Document every accepted and rejected adjustment with evidence citation
Phase 3 — Ratio Analysis and Stress Testing
- ☐ Calculate Total Leverage, Senior Leverage, DSCR, and FCCR on lender-adjusted EBITDA base
- ☐ Confirm all ratios use the same EBITDA denominator — reconcile to covenant definition
- ☐ Run base case, downside (-20% EBITDA), and severe stress (-30% EBITDA) scenarios
- ☐ Test covenant headroom at each scenario — identify the EBITDA level at which the first covenant trips
- ☐ Confirm liquidity independently from EBITDA covenants (minimum liquidity, cash dominion triggers)
Phase 4 — Questions to Ask Management
- ☐ “Walk me through each add-back line — show me the invoice or GL entry.”
- ☐ “Has this cost recurred in any prior year? Show me three years.”
- ☐ “What is the market rate for your role, and how does your current compensation compare?”
- ☐ “When exactly will the projected cost savings appear in financials, and what is the implementation plan?”
- ☐ “Has your revenue recognition policy or inventory costing methodology changed in the past 24 months?”
Key Takeaways
- 🔑 Never underwrite to management’s EBITDA. Build lender-adjusted EBITDA independently, starting from GAAP-reported results and applying the CARVE test to each proposed add-back. The spread between management’s number and yours is a direct measure of credit risk.
- 🔑 Unsupported add-backs are a leverage trap. A single $500K of rejected add-backs on a $1.9M EBITDA base can move effective leverage from 3.5x to 4.4x — changing pricing tier, covenant architecture, and approval authority in one adjustment.
- 🔑 The credit market is enforcing tighter standards. With leveraged loan default rates near 7.5% in 2025 — nearly double the historical average — and 56% of defaults taking the form of distressed exchanges, the cost of weak underwriting discipline is no longer theoretical.
- 🔑 QoE is becoming a regulatory baseline, not a best practice. The SBA’s October 2026 mandate for independent QoE reports on $3M+ acquisitions reflects a broader institutional recognition that lender reliance on unverified management EBITDA is a systemic vulnerability.
- 🔑 Stress test the EBITDA base, not just the headline leverage. Underwrite to what the business can sustain in a 25–30% EBITDA contraction. If covenant headroom disappears under that scenario, the deal needs more equity, tighter covenants, or a smaller facility — not a more aggressive add-back schedule.


