
Why One Loan Is Not Always One Lender
When a private equity firm acquires a mid-sized business, the financing question is rarely simple. Traditional bank loans cap out at conservative leverage levels. Mezzanine debt adds a second lender, a second credit agreement, a second set of covenants, and weeks of additional negotiation. For time-sensitive buyouts, that complexity is a deal killer.
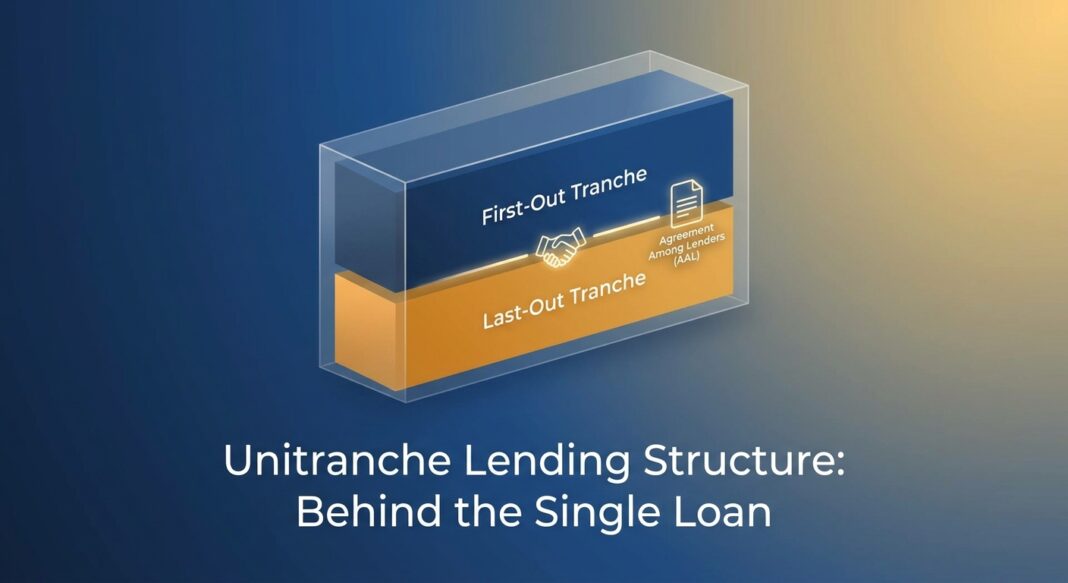
Enter the unitranche loan — the structure that now dominates middle-market private credit. To the borrower, a unitranche looks and feels like a single, first-lien term loan from one lender: one credit agreement, one covenant package, one closing. Behind the scenes, however, the loan is often split between two lending parties — a bank or conservative credit fund taking the First-Out position and a private credit fund absorbing the riskier Last-Out piece — governed by a confidential Agreement Among Lenders (AAL) that the borrower typically never sees.
Understanding this mechanism is not just academic. For investors evaluating private credit funds, it determines recovery risk. For operators financing a transaction, it determines speed, cost, and flexibility. As bank lending standards continue to tighten in 2026, knowing how unitranche works has never been more practically valuable.
What Is a Unitranche Loan?
A unitranche facility is a single-tranche term loan that blends senior and subordinated debt into one instrument, governed by one credit agreement, with one set of collateral documents granting liens for the benefit of all lenders in the facility. As legal practitioners at the American Bar Association (2025) describe it, the structure offers borrowers a streamlined, one-stop facility that is faster, more certain in execution, and potentially more cost-effective than a traditional bifurcated debt stack.
The key innovation is what happens between lenders. In a traditional first-lien / second-lien structure, each lender group has its own loan agreement and the relationship between them is governed by an intercreditor agreement. In a unitranche, all lenders share a single lien. Their internal economics — who gets paid first, who controls enforcement, how payments split in a default — are governed by the Agreement Among Lenders (AAL).
The Lucosky Brookman restructuring team explains it precisely: the AAL synthetically separates lenders into a First-Out tranche and a Last-Out tranche, effectively mimicking the senior/junior lien structure while maintaining a single credit agreement with the borrower. According to Mayer Brown (2023), the unitranche structure has several advantages, including typically quicker execution and in some cases a lower cost of capital to the borrower, as the blended rate smooths out what would otherwise be a more expensive subordinated tranche.
How It Works: A Concrete Example
Consider a private equity firm acquiring a business valued at $700 million — a 14x multiple on $50 million of EBITDA. The sponsor plans to fund the deal with $300 million of equity and $400 million of debt. A conventional bank can offer cheaper financing at SOFR + 3.75%–4.00%, but will typically lend only up to roughly $200 million (4x EBITDA). That leaves a $200 million financing gap.
A unitranche lender steps in and offers the full $400 million at a blended rate of SOFR + 5.25% — one loan, one close, one set of covenants. The borrower signs a single credit agreement. Internally, the AAL divides the loan: a bank or conservative fund takes the First-Out position (roughly the $200 million senior-equivalent slice) at a lower spread, say SOFR + 3.75%. A private credit fund absorbs the Last-Out position (the remaining $200 million junior-equivalent slice) at a higher spread, say SOFR + 6.75%. The blended rate to the borrower lands at approximately SOFR + 5.25%.
Under the AAL, Jones Day notes that First-Out lenders receive a lower proportion of the blended margin but are first to receive interest and principal repayments. Cash interest flows to First-Out lenders while PIK (payment-in-kind) interest is typically allocated to Last-Out lenders. First-Out lenders also control any enforcement process — a critical distinction in a stress scenario.
From the borrower’s perspective, according to Wall Street Prep, unitranche debt is essentially an agreement with just one lender: a single set of contractual terms, minimal mandatory amortization, and prepayment penalties that are often zero or minimal — giving operators more flexibility to refinance or recapitalize as conditions change.
Current Market Relevance
Unitranche financing is no longer a niche product. CTA Acquisitions (June 2026) observes that it now dominates the lower middle-market direct lending channel, with issuance growing from roughly $20 billion annually in 2015 to over $200 billion in 2025 as direct lenders displaced traditional bank syndication for sub-$1 billion EBITDA borrowers. Pricing in Q2 2026 sits at approximately SOFR + 500–700 basis points for typical lower-middle-market transactions, with 3-month Term SOFR at roughly 4.3%.
That backdrop matters because banks are still tightening. The Federal Reserve’s April 2026 SLOOS reported that banks tightened lending standards and all surveyed terms for C&I loans to firms of all sizes in Q1 2026, with the most widely cited changes including higher premiums on riskier loans, stricter loan covenants, and lower maximum credit line sizes. This sustained tightening cycle — now running through multiple consecutive SLOOS surveys — is the structural tailwind redirecting middle-market borrowers toward private credit lenders offering unitranche facilities.
The scale of that redirection is measurable. According to PIMCO (citing Preqin, March 2026), total AUM in North American direct lending portfolios increased roughly sevenfold over the past decade, from $93 billion in 2015 to approximately $644 billion by year-end 2025. According to McKinsey (June 2026), the seven largest private credit platforms grew AUM at approximately 20% annually from 2022 to 2025, and private credit now funds over 80% of all LBO transactions.
On the lender side, Valuation Research Corporation (Q2 2026) reports that unitranche yields remained broadly stable on a spot basis in Q2 2026, with credit spreads largely unchanged as three-month Term SOFR edged up to 3.69% in June. Hamilton Lane (April 2026) notes that wider spreads, higher-for-longer rates, and bank retrenchment are improving pricing and terms for disciplined lenders — framing the current environment as one favoring lenders with strong underwriting and durable cash flow focus.
| Metric | Value | Source |
|---|---|---|
| LMM Unitranche Spread (Q2 2026) | SOFR + 500–700 bps | CTA Acquisitions, Jun 2026 |
| 3-Month Term SOFR (June 2026) | ~3.69% | VRC Q2 2026 |
| N. American Direct Lending AUM (YE 2025) | ~$644 billion | PIMCO / Preqin, Mar 2026 |
| Unitranche Annual Issuance (2025) | >$200 billion | CTA Acquisitions, Jun 2026 |
| Covenant-Lite Share of Direct Lending (2025) | 21% (up from 4% in 2023) | McKinsey / Proskauer, Jun 2026 |
Decision Framework: Investors and Operators
For Investors Evaluating Private Credit Funds:
- Ask whether the fund holds First-Out or Last-Out positions. Last-Out holders absorb losses first in a default and receive PIK rather than cash interest in stress. The higher spread they earn compensates for this subordination — but recovery rates will diverge sharply in a downturn.
- Scrutinize the AAL terms. Not all AALs are equal. Investors evaluating a direct lending fund should consider how the fund’s AALs define control rights during enforcement, who can block amendments, and what the voting thresholds are for restructuring scenarios.
- Assess covenant quality. McKinsey data shows covenant-lite direct lending transactions rose to 21% of deals in 2025, up from just 4% in 2023. Covenant-lite loans reduce early warning signals for lenders. Investors may consider evaluating whether a fund’s portfolio is concentrated in cov-lite structures and whether that reflects competitive pressure rather than deliberate underwriting.
- Consider concentration risk. Unitranche deals often involve one to three lenders. Lender-concentration risk — where a shift in a fund’s strategy or capacity can affect a borrower’s refinancing options — is a distinct consideration versus broadly syndicated credits.
For Operators Evaluating Unitranche Financing:
- Speed is a genuine advantage. Private credit lenders offering unitranche facilities can typically close within approximately four weeks, while bank-syndicated deals may require six to eight weeks, according to Private Capital Global.
- Price the all-in cost carefully. Headline spread is only part of the picture. Original issue discount (OID), amendment fees, and prepayment premiums over the loan life can materially increase the effective cost of capital above the quoted SOFR + spread.
- Evaluate lender flexibility post-close. Because unitranche lenders typically hold loans to maturity rather than selling into secondary markets, the relationship dynamic matters. A lender who knows your business and holds a concentrated position has both the incentive and the capability to work constructively through covenant breaches or business volatility.
Key Takeaways
- One loan, two risk positions: A unitranche appears as a single first-lien facility to the borrower, but the AAL internally bifurcates it into First-Out (senior-equivalent) and Last-Out (junior-equivalent) tranches with distinct economics and control rights.
- Bank retrenchment is the structural driver: Consecutive Federal Reserve SLOOS surveys through Q1 2026 confirm tightening bank C&I lending standards, redirecting middle-market borrowers toward private credit unitranche lenders who can provide higher leverage in a single facility.
- Pricing carries real complexity: At SOFR + 500–700 bps for lower-middle-market transactions in Q2 2026, all-in costs exceed the headline rate once OID and fees are incorporated. Operators may find this cost justified by execution speed and structural flexibility.
- Covenant erosion is a risk to monitor: The rise of covenant-lite unitranche deals — from 4% to 21% of direct lending transactions between 2023 and 2025 — reduces lender early-warning mechanisms. Investors may consider evaluating the trade-off between borrower-friendly terms and lender protection in any fund they assess.
- The AAL is the document that matters most in stress: In a distressed scenario, how the AAL allocates payments, remedies, and voting control will determine outcomes for each lender group. Understanding AAL mechanics is essential for any investor participating in, or operator financing through, a unitranche structure.


