
The Concept That Explains Everything in Private Credit
When someone says they “invest in private credit,” that phrase alone tells you almost nothing about the risk they are actually taking. A senior secured direct lending fund and a mezzanine debt fund are both classified as private credit — but they occupy entirely different positions in the repayment hierarchy when a borrower runs into trouble. That hierarchy has a name: the capital stack. Understanding it is the single most important foundational skill for anyone evaluating private credit, whether as an investor allocating capital or as a business owner raising it.
What the Capital Stack Is and How It Works
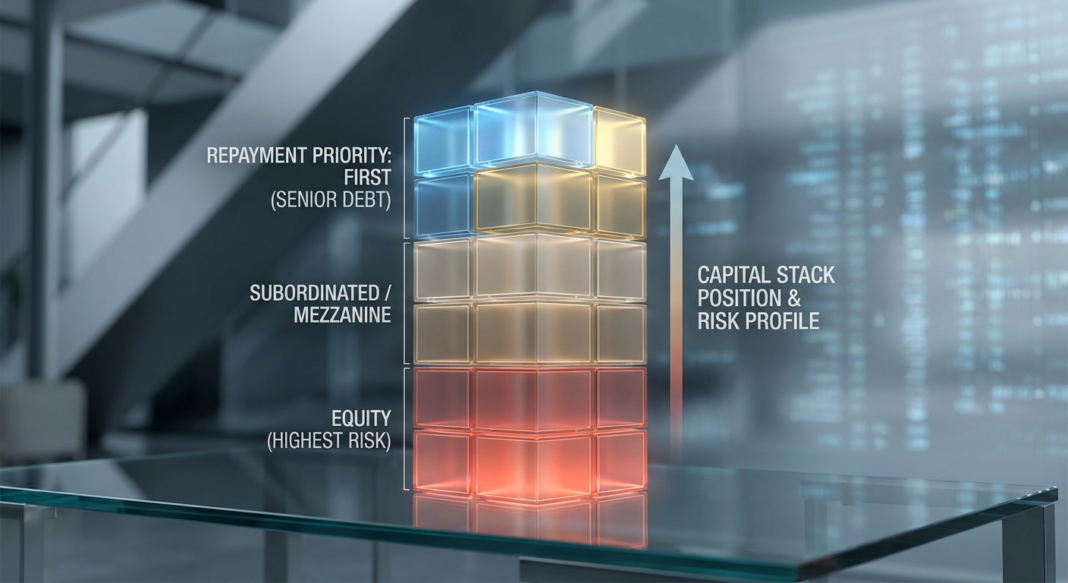
The capital stack is the structured hierarchy of all financial claims on a company’s assets and cash flows. It determines, with legal precision, who gets paid first and who absorbs losses first when a borrower defaults or is liquidated. According to BIP Wealth, the layers near the top of the stack — working capital facilities and senior secured debt — are repaid before all others and are typically backed by tangible assets such as cash, receivables, equipment, and real property. The layers near the bottom — preferred equity and common equity — absorb losses first and receive proceeds last.
The standard capital stack, from highest to lowest priority, looks like this:
- Senior Secured Debt (First Lien): First in line for repayment; backed by a direct claim on collateral. Lowest yield, lowest risk among lenders.
- Second Lien / Unitranche: Junior to first-lien debt but senior to mezzanine. A unitranche combines first- and second-lien into a single blended instrument.
- Mezzanine / Subordinated Debt: Sits below senior debt; typically carries higher coupons and may include equity warrants to compensate for elevated risk.
- Preferred Equity: Has preference over common equity in distributions and liquidation, but ranks behind all debt.
- Common Equity: Last in line. Absorbs all losses before any lender is impaired.
Subordination is the legal mechanism that enforces these priorities. A subordinated lender formally agrees — in writing, via an intercreditor agreement — that its claims will only be satisfied after senior obligations are fully repaid. This is not a gentleman’s agreement; it is contractually binding in bankruptcy proceedings.
A Concrete Example with Numbers
Consider a private equity-sponsored acquisition of a mid-market manufacturing company with an enterprise value of $100 million. The deal is financed as follows:
- Senior Secured Term Loan: $50 million (50% of enterprise value)
- Mezzanine Debt: $20 million (20% of enterprise value)
- Equity Contribution: $30 million (30% of enterprise value)
Now suppose the business underperforms. Two years later, lenders declare a default and the company is sold in a distressed process for $60 million. Here is how the proceeds flow:
- The senior secured lender is repaid in full: $50 million recovered on $50 million lent — 100 cents on the dollar.
- The remaining $10 million flows to the mezzanine lender, who recovers $10 million on a $20 million position — 50 cents on the dollar.
- The equity holders receive nothing — a complete loss of their $30 million.
This example illustrates why the equity cushion — the equity sitting below a debt position — is such a critical protective buffer for lenders. In this scenario, the 30% equity layer had to be entirely wiped out before the senior lender lost a single dollar. The mezzanine lender’s risk materialized precisely because that cushion was insufficient to protect their junior position once enterprise value declined.
Current Market Relevance
The capital stack is not just a theoretical framework — it is actively shaping where capital flows in 2026’s private credit landscape. Several current dynamics make this foundational concept more relevant than ever:
According to PitchGrade’s 2026 Private Credit Primer, global private credit AUM has surpassed $1.7 trillion as of Q1 2026, with the five largest managers — Ares, Apollo, Blackstone, Blue Owl, and HPS — collectively overseeing more than $800 billion of that total. This scale reflects structural, not cyclical, demand.
A key driver of that structural shift is regulatory pressure on banks. As noted by PitchGrade, Basel III capital rules require banks to hold significant Tier 1 capital against leveraged loans, and OCC Leveraged Lending Guidance — reinforced in 2022 — effectively discourages banks from underwriting deals with debt-to-EBITDA ratios above 6.0x. Transactions above that threshold now flow almost entirely to private credit funds, which are not subject to the same regulatory constraints. The practical result: more than 75% of leveraged buyout financing in deals below $500 million in EBITDA is now provided by private credit lenders rather than banks.
For senior secured direct lending specifically, Long Angle’s 2026 Private Credit Guide notes that default rates for direct lending have remained under 4% since 2021, citing Proskauer’s Private Credit Default Index — a reflection of the protective power of senior position and strong covenant packages in well-underwritten deals.
Pricing varies significantly by stack position. Per PitchGrade, middle-market senior secured loans currently price at approximately SOFR + 500–650 basis points, while large-cap senior loans price tighter at SOFR + 425–500 basis points. Mezzanine and subordinated debt commands materially higher all-in yields to compensate investors for their junior position — illustrating the direct relationship between stack position and required return.
Decision Framework: Investors and Operators
For Investors Evaluating Private Credit:
- Before analyzing any private credit fund’s yield, identify where in the stack it lends. A higher headline yield may simply reflect a lower position — and therefore greater loss exposure — not superior manager skill.
- Evaluate the loan-to-value (LTV) ratio and the size of the equity cushion subordinate to the fund’s debt position. A larger cushion provides more buffer before lender capital is impaired.
- Assess intercreditor agreements in multi-tranche deals. These documents define the practical enforceability of subordination in a restructuring scenario.
- Consider that senior secured strategies have historically delivered strong risk-adjusted returns with lower volatility — which is why, as Blackstone notes, direct lending managers typically adopt a highly defensive, first-lien-focused investment approach.
For Business Operators Raising Capital:
- Recognize that each layer of the capital stack carries a different cost. Senior debt is the cheapest form of non-dilutive financing; equity is the most expensive but carries no repayment obligation.
- Mezzanine and subordinated debt can bridge a gap between senior debt capacity and equity — useful when senior lenders will not stretch leverage, but equity dilution is undesirable.
- Be aware that covenants and collateral requirements intensify as you move up the stack toward senior secured lenders; junior capital providers may offer more structural flexibility in exchange for a higher coupon or equity participation.
Key Takeaways
- Position determines risk: In private credit, where a lender sits in the capital stack is the primary driver of loss probability — not the headline interest rate.
- Equity cushion is the first line of defense: Every dollar of equity below a debt position must be fully extinguished before that lender suffers a loss. Larger cushions equal greater protection.
- Subordination is contractual, not conceptual: Intercreditor agreements make repayment priority legally binding and enforceable in bankruptcy — understanding them is essential due diligence.
- Yield reflects position: Higher coupons in mezzanine or subordinated debt are compensation for junior stack exposure, not evidence of a better deal. Investors should evaluate risk-adjusted returns, not absolute yield.
- The private credit market has structurally shifted toward non-bank lenders: With banks constrained by regulation, private credit funds now dominate middle-market lending — making capital stack literacy more critical than ever for both allocators and borrowers.


