
Where You Stand in Line Determines Everything
When a business borrows money, not all lenders are created equal. Some will be repaid first. Others will wait. A few may never see their money again if things go wrong. This hierarchy — called the capital stack — is arguably the single most important concept in private credit. It determines your risk exposure before the first interest payment is ever made, and it shapes every return expectation in the structure.
For investors evaluating private credit funds, understanding where a loan sits in the capital stack is more revealing than any headline yield figure. For business owners seeking capital, the stack determines how much control you retain, what your borrowing costs will be, and what obligations you accept. In both cases, position is everything.
What the Capital Stack Actually Is
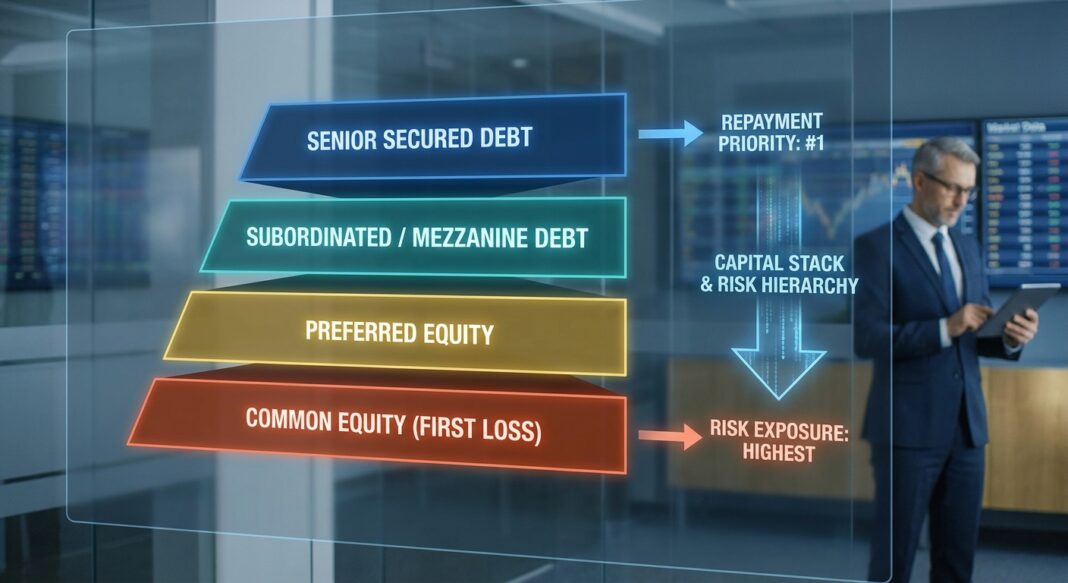
The capital stack is the layered structure of all financial claims on a company’s assets and cash flows, ranked by repayment priority. According to BIP Wealth, the stack determines who gets paid first — and who absorbs losses first — when a borrower encounters difficulty.
From top to bottom, the typical capital stack moves through four broad layers:
- Senior Secured Debt: First priority claim, backed by collateral (receivables, equipment, real property). Lowest yield, lowest risk. Repaid before all other capital providers.
- Subordinated / Mezzanine Debt: Junior to senior secured lenders but senior to equity. Higher coupon to compensate for standing further back in the repayment line. May include equity warrants.
- Preferred Equity: No fixed collateral claim, but receives distributions before common equity holders. Hybrid characteristics of both debt and equity.
- Common Equity: Last in line. Absorbs first losses. Highest potential upside, highest potential for total loss.
Subordination is the legal mechanism that enforces this hierarchy. When a borrower signs a subordinated debt agreement, they are contractually agreeing that the subordinated lender will only be repaid after senior obligations are satisfied. In a liquidation, this order is legally binding — not negotiable.
How It Works: A Concrete Example
Consider a private equity-backed manufacturing company valued at $100 million. The deal is financed as follows:
- $55 million — Senior Secured Term Loan (55% of capital): Provided by a private credit direct lender at SOFR + 575 basis points. First lien on all company assets.
- $15 million — Mezzanine Debt (15% of capital): Subordinated to the senior loan. Priced at a fixed 13%, with equity warrants attached.
- $30 million — Sponsor Equity (30% of capital): Common equity held by the private equity firm and management.
Now suppose the business deteriorates and is liquidated at $65 million — a 35% decline from the original valuation.
Here is how the recovery flows through the stack:
- Senior secured lenders recover their full $55 million — 100 cents on the dollar.
- Mezzanine lenders recover the remaining $10 million — roughly 67 cents on the dollar, absorbing a $5 million loss.
- Equity holders recover $0 — their entire $30 million is wiped out.
This example illustrates the concept of equity cushion: the amount of subordinated capital below a senior lender that must be destroyed before the senior lender suffers any loss. In this case, the senior lender had a $45 million equity and mezzanine cushion protecting a $55 million loan — providing substantial downside protection even in a severe stress scenario.
Current Market Relevance
Understanding capital stack position is especially timely in 2026, as private credit has matured into a dominant force in corporate finance. Consider the scale of the market today:
- According to PitchGrade’s 2026 Private Credit Primer, global private credit AUM has exceeded $1.7 trillion as of Q1 2026, with senior secured direct lending representing the largest single strategy within the asset class.
- The same source notes that 75% or more of leveraged buyout financing for companies below $500 million in EBITDA is now provided by private credit funds rather than banks — a structural shift driven by post-GFC bank regulation.
- Middle market direct lending is currently priced at approximately SOFR + 500–650 basis points, while large-cap direct lending trades at SOFR + 425–500 basis points, reflecting the risk premium associated with smaller borrowers, per PitchGrade (2026).
- According to Long Angle’s Private Credit Investment Guide 2026, default rates for direct lending have remained below 4% since 2021, a figure attributed in part to the protective positioning of senior secured debt and the robust covenant structures that accompany it.
- As noted by Columbia Threadneedle Investments, middle market borrowers in the direct lending universe typically carry leverage of 6x–8x EBITDA with average credit ratings of B- to CCC+, underscoring why structural seniority — not just credit quality — is the primary risk management tool for private credit lenders.
| Metric | Data Point | Source |
|---|---|---|
| Global Private Credit AUM | >$1.7 trillion (Q1 2026) | PitchGrade |
| Middle Market Spread (Senior) | SOFR + 500–650 bps | PitchGrade |
| Direct Lending Default Rate (since 2021) | <4% | Long Angle / Proskauer |
| Private Credit Share of LBO Financing (<$500M EBITDA) | >75% | PitchGrade |
| Avg. Middle Market Borrower Leverage | 6x–8x EBITDA | Columbia Threadneedle |
Decision Framework: Investors and Operators
For Investors Evaluating Private Credit Funds: Not all private credit is the same risk. When reviewing a fund or BDC, investors consider which layer of the capital stack the manager targets. A fund lending exclusively at the senior secured level is structurally different from one providing mezzanine or subordinated capital — even if both carry the label "private credit." As BIP Wealth notes, a subordinated debt fund and a senior secured direct lending fund "occupy very different positions in the repayment line." Institutional allocators evaluate: (1) average loan-to-value or loan-to-EBITDA ratios across the portfolio, (2) the percentage of first-lien versus subordinated positions, (3) historical recovery rates by tranche in stress periods, and (4) covenant tightness as a function of stack position.
For Business Owners Seeking Capital: Operators evaluate the capital stack from the opposite angle — not where to stand in line, but how much of the stack they can access and at what cost. Senior secured debt is the cheapest form of external capital, but it comes with covenant obligations and collateral requirements. Mezzanine and subordinated capital costs more but is typically more flexible and does not require the same asset coverage. Equity is the most expensive capital over a long horizon (dilution of ownership) but carries no fixed repayment obligation. Business owners evaluate the stack by asking: how much senior debt capacity do my assets and cash flows support, and at what point does subordinated capital or equity become necessary to close a financing gap?
Key Takeaways
- Position determines risk, not just yield: A higher coupon on subordinated debt compensates for standing further back in the repayment line — the yield premium is structural, not incidental.
- Equity cushion is a lender’s primary safety net: The more junior capital beneath a senior loan, the larger the buffer before senior lenders face losses in a downside scenario.
- Private credit spans multiple stack positions: Investors should always identify whether a fund targets senior secured, mezzanine, or subordinated debt — "private credit" alone describes an asset class, not a risk profile.
- Bank retreat has accelerated senior secured opportunities: With more than 75% of sub-$500M EBITDA LBO financing now done by private lenders, senior secured direct lending has become a mainstream institutional strategy, not a niche alternative.
- Covenants reinforce stack protection: As noted by DeMarche’s 2026 Private Credit Overview, financial covenants — such as minimum DSCR or leverage limits — serve as early warning systems that allow senior lenders to act before subordinated capital is fully eroded.


