
The Repayment Line Nobody Talks About—Until It’s Too Late
When a business borrows money, every lender and investor sits somewhere in an invisible queue. That queue has a name: the capital stack. In a healthy company, the queue barely matters—everyone gets paid. But when a borrower runs into trouble, your position in that queue becomes the single most important variable in whether you recover your capital or absorb a loss.
Understanding the capital stack is not optional knowledge for anyone evaluating private credit funds, direct lending platforms, or structured financing deals. It is the foundational framework. Two private credit funds can both market themselves as “private credit” while occupying positions so different in the repayment hierarchy that they carry materially different risk profiles. This article explains how the stack works, what each layer means in practice, and how both investors and business owners should think about it.
What the Capital Stack Is and How It Works
The capital stack is the hierarchy of financial claims on a company’s assets and cash flows. Every dollar of financing a business raises—whether debt or equity—occupies a rung on this ladder. The defining rule is straightforward: higher up the stack means first to be repaid; lower down means last to be repaid and first to absorb losses.
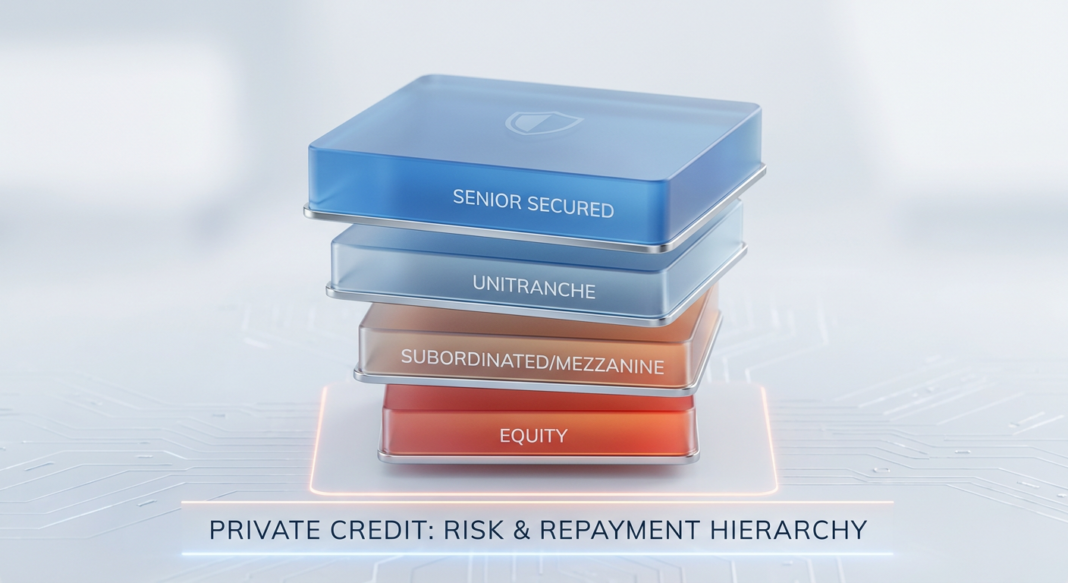
According to BIP Wealth, the stack is typically organized from top to bottom as follows:
- Working Capital & Senior Secured Debt: First-priority claim, backed by tangible collateral such as cash, receivables, equipment, or real property. In a liquidation, these lenders are paid before all others.
- Unitranche Debt: A blended instrument that combines senior and subordinated debt into a single facility, typically used in leveraged buyouts. It carries a blended interest rate sitting between pure senior and pure subordinated pricing.
- Subordinated / Junior Debt: Sits behind senior lenders. Commands a higher interest rate to compensate for the additional risk. Typically unsecured and can be wiped out entirely in a bankruptcy scenario before senior lenders take losses.
- Mezzanine Debt: A hybrid layer bridging debt and equity. Often structured with warrants that give the lender an option to convert debt into equity under specified conditions. Carries higher rates than senior debt to reflect its junior position.
- Preferred & Common Equity: Residual claimants. Equity holders are paid last—only after every debt obligation is satisfied. They absorb the first dollar of loss when asset values decline.
As Gridline notes, this hierarchy is not merely theoretical—it governs the legal order of payments in a bankruptcy proceeding and shapes every pricing, covenant, and collateral negotiation before a deal closes.
A Concrete Example: The Same Company, Three Different Risk Profiles
Consider a middle-market manufacturing company with $50 million in total enterprise value (TEV) and the following capital structure:
- $20 million Senior Secured Term Loan — secured by equipment and receivables, first lien
- $10 million Subordinated Note — unsecured, second priority
- $20 million Equity — common shares held by a private equity sponsor
Now assume the company deteriorates and is sold in a distressed process for $22 million—less than half its original valuation.
Here is how each class recovers:
- Senior Secured Lender: Recovers the full $20 million. Every dollar of their principal is returned because the sale proceeds exceed their claim.
- Subordinated Noteholder: Receives the remaining $2 million against a $10 million claim—a recovery of just 20 cents on the dollar.
- Equity Holder: Receives nothing. The equity is fully wiped out.
Same company. Same distress event. Three entirely different outcomes—determined entirely by capital stack position. The equity cushion sitting below the senior lender ($30 million in subordinated debt and equity at origination) absorbed the damage before the senior lender’s capital was threatened. This protective buffer is why senior secured lenders price their debt at lower yields than subordinated lenders, and why subordinated lenders demand higher yields to compensate for the risk they are explicitly accepting.
Current Market Relevance: Where the Stack Stands in 2026
Private credit’s rapid ascent has made stack-position literacy more urgent than ever for capital allocators. According to Long Angle’s Private Credit Investment Guide 2026, private credit now represents approximately 20% of the total leveraged credit market in the United States—a share captured almost entirely from banks and public syndicated loan markets that have pulled back since the Global Financial Crisis.
That same guide reports that direct lending default rates have remained below 4% since 2021, citing Proskauer’s Private Credit Default Index—a figure that reflects both the credit quality of underlying borrowers and the structural protection afforded by senior secured positioning. Critically, low default rates do not tell the full story; recovery rates on defaulted loans are heavily determined by where in the stack a lender sits when a default occurs.
As Meketa’s Private Credit Primer highlights, institutional investors—pension funds, insurance companies, and sovereign wealth funds—have expanded their private credit allocations precisely because senior secured direct lending offers what public investment-grade bonds increasingly cannot: floating-rate income, covenant protections, and collateral-backed downside buffers in a higher-for-longer rate environment.
The growth of unitranche structures is a notable evolution in the current market. According to Gridline, unitranche debt has become a preferred tool in sponsor-backed leveraged buyouts, allowing a single lender to provide a full financing solution at a blended rate that sits between senior and subordinated pricing. For borrowers, the benefit is execution speed and structural simplicity. For lenders, it concentrates risk in a single relationship but requires particularly disciplined underwriting given the hybrid exposure.
Decision Framework: Investors and Operators
For Investors Evaluating Private Credit Funds
- Ask where in the stack the fund lends. “Private credit” is not a single risk profile. A senior secured direct lending fund and a mezzanine fund operate under fundamentally different loss scenarios. Evaluate each on its own terms.
- Examine the equity cushion beneath you. The thickness of subordinated capital and equity sitting below a senior lender’s position is the structural margin of safety. Thinner cushions mean smaller valuation declines can threaten recovery.
- Assess collateral quality. Senior secured claims backed by liquid, tangible assets—receivables, real property, equipment—provide more reliable recovery than those backed by intangible cash flow projections.
- Understand the liquidity trade-off. As BIP Wealth notes, private credit investments typically carry specific redemption windows rather than daily liquidity. This illiquidity is structural and should be evaluated against the yield premium earned for accepting it.
For Business Owners and Operators Raising Capital
- Match your financing need to the right stack layer. Senior secured debt is cheapest but requires collateral and strong cash flow coverage. Mezzanine and subordinated debt cost more but may be accessible when senior capacity is exhausted or assets are insufficient for full collateralization.
- Understand what covenants accompany each layer. As Carta explains, private credit lenders negotiate terms directly with borrowers, which means covenant structures vary significantly by lender and stack position. Junior lenders—facing greater loss risk—often impose tighter operational covenants to protect their position.
- Consider dilution versus cost. Raising equity avoids debt service obligations but dilutes ownership. Raising debt preserves ownership but creates fixed payment obligations. The capital stack is ultimately a tool for optimizing this trade-off against current business conditions.
Key Takeaways
- Position is everything in a default. The capital stack determines recovery before any legal process begins. Senior secured lenders recover first; equity absorbs losses first. Every layer in between is priced to reflect exactly where it stands.
- “Private credit” is not one risk profile. A senior secured direct lending fund and a mezzanine fund are both private credit—and they are not remotely comparable in risk, return, or loss exposure. Always identify the stack position before evaluating a strategy.
- Equity cushion is the margin of safety for debt investors. The thicker the subordinated capital and equity sitting below a senior lender, the larger the decline in company value that can occur before senior principal is threatened.
- Unitranche structures simplify execution but concentrate risk. Combining senior and subordinated debt into one facility speeds deal closing for borrowers and lenders alike—but requires rigorous underwriting because the lender is absorbing exposure across two stack layers simultaneously.
- Default rates alone do not tell the full story. Low headline default rates in direct lending are meaningful, but recovery rates on defaulted loans—driven directly by stack position and collateral quality—are what ultimately determine realized losses for investors.


