
The Capital Challenge: Growth-Stage Companies Pursuing Bolt-On Acquisitions
You have proven unit economics, $5M–$20M in revenue, and a target on the table. The acquisition price is $15M. Your bank will stretch to $8M on a senior term loan. That leaves a $7M gap — and how you fill it will define your cost of capital, your equity dilution, and your operational flexibility for the next five years.
This is the quintessential growth-stage capital challenge: the business is too mature for venture equity terms, too early for broadly syndicated leveraged finance, and too acquisitive for organic cash flow alone. Navigating it requires a deliberate capital stack strategy — not a single funding call, but a sequenced architecture that matches each layer of capital to its appropriate risk, cost, and structural role.
Mapping the Capital Stack for a Growth-Stage Acquisition
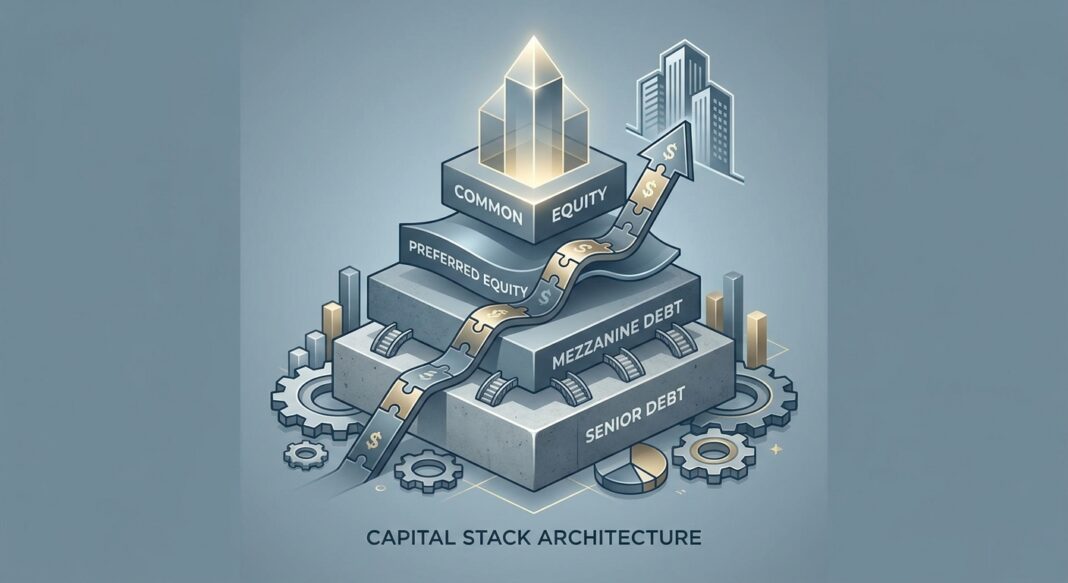
The capital stack for a $15M acquisition at a growth-stage company typically involves three to four distinct layers, each carrying different pricing, seniority, and negotiating dynamics. Moving from bottom to top:
Layer 1: Senior Secured Debt — The Anchor
Senior bank debt or a direct lending facility secured by company assets and cash flows forms the foundation. For a software or services business generating $3M–$5M in EBITDA, a lender will typically advance 2.5x–3.5x leverage at a floating rate. In the current rate environment, all-in pricing sits in the SOFR + 250–400 bps range for bank facilities, or SOFR + 450–600 bps for direct lending unitranche structures. This layer provides the cheapest capital but carries the most structural restrictions: financial maintenance covenants (leverage ratio, fixed charge coverage), negative covenants limiting additional debt and capex, and collateral requirements. As [re-cap.com](https://www.re-cap.com/en-gb/blog/capital-structure-vs-capital-stack) notes, senior debt sits at the bottom of the stack precisely because it has the highest repayment priority and the lowest risk — and lenders price it accordingly.
Layer 2: Mezzanine or Subordinated Debt — The Bridge
Mezzanine capital fills the gap between what senior lenders will advance and what equity providers want to deploy. It is subordinated to senior debt in the repayment waterfall, which means it absorbs more risk — and demands higher returns. Typical pricing ranges from 12%–18% all-in, often structured as a combination of cash pay interest (8%–12%) and PIK (payment-in-kind) interest that accrues to the principal balance rather than requiring immediate cash outflow. Many mezz structures also include an equity kicker: warrants or a co-investment right representing 1%–5% of the business, providing the lender with upside participation beyond the coupon. This layer is covenant-lite relative to senior debt, typically using incurrence-based tests rather than maintenance covenants — meaning covenants are only triggered if the borrower takes a specific action (incurs more debt, makes a distribution), not simply by operating below a financial threshold.
Layer 3: Preferred Equity — Structured Flexibility
Where debt is unavailable or the leverage burden is too high, preferred equity steps in. Preferred instruments sit above common equity in the liquidation waterfall but below all debt. Returns are delivered via a preferred dividend (often 8%–14%, sometimes PIK), a liquidation preference (typically 1x invested capital), and participation rights in upside. For growth-stage operators, preferred equity is more expensive than debt on an annualized basis but preserves operating flexibility — there is no scheduled repayment, no acceleration risk, and generally no financial maintenance covenants. As [firstratefunding.net](https://www.firstratefunding.net/optimizing-capital-structure-how-to-scale-growth-without-losing-control/) observes, the true cost of equity must account for dilution, governance rights, and liquidation preferences — not just the headline dividend rate.
Layer 4: Common Equity — The Residual Claim
Founder equity, management rollover, and sponsor co-investment sit at the top of the stack, bearing the most risk and capturing the most upside. In a growth-stage acquisition, the goal is to minimize how much new common equity is issued at current valuation — every dollar of debt or preferred equity placed below common equity is a dollar of acquisition price funded without diluting existing ownership.
The Gap Capital Playbook: Quantify, Prepare, Run, Negotiate
Step 1 — Quantify the Gap
Start with the acquisition price and work backward. Total enterprise value of the target: $15M. Senior debt capacity based on your EBITDA and lender appetite: $8M. Seller note or earnout (if applicable): $1M. Remaining gap to close: $6M. This $6M is your “gap capital” — the quantum that requires a structured solution outside of conventional bank financing. Model three scenarios: (a) fill the gap with mezz debt, (b) fill it with preferred equity, (c) blend both. For each scenario, calculate your post-close leverage ratio, annual debt service coverage, and pro-forma equity dilution. The scenario that maintains coverage above 1.20x FCCR while keeping total leverage below 5.0x EBITDA and limiting dilution below 15% of common equity is your optimal structure.
Step 2 — Prepare the Materials
Gap capital providers — mezzanine funds, family offices, BDCs, and credit opportunity funds — underwrite to a different thesis than senior lenders. They want to see: (1) a clear use-of-proceeds memo showing how the acquisition creates EBITDA accretion; (2) a three-year integrated financial model with sensitivity tables on revenue growth and margin compression; (3) a management presentation articulating the strategic rationale, competitive moat, and exit pathway; and (4) a clean cap table showing pre- and post-transaction ownership. As [alvren.com](https://www.alvren.com/insights/capital-stack-design-how-to-fund-the-next-24-months-without-boxing-yourself-in) notes, a clear capital plan and governance narrative materially shortens due diligence timelines with institutional capital providers.
Step 3 — Run a Structured Process
Approach four to six gap capital providers simultaneously, not sequentially. Create competitive tension. Send a structured term sheet request with a defined response deadline. Require providers to specify: coupon structure (cash pay vs. PIK split), warrant coverage or equity participation, covenant package, board observer rights, and any change-of-control provisions. Evaluate responses across all five dimensions — not just price. A 14% all-in mezz facility with a 3% warrant and maintenance covenants may be more restrictive than a 16% preferred equity instrument with no covenants and no scheduled repayment.
Step 4 — Negotiate the Structure
The most negotiable terms in a gap capital structure are: (a) the PIK vs. cash pay split — push for more PIK in years one and two to preserve cash flow during integration; (b) warrant coverage — negotiate coverage as a percentage of fully diluted equity, not a fixed share count; (c) the definition of EBITDA in any covenant calculations — ensure it includes pro-forma synergies and excludes non-recurring transaction costs; and (d) the call protection schedule — a 2%/1%/0% step-down over three years is standard, but a no-call period in year one can be negotiated away for creditworthy borrowers with strong EBITDA visibility. As [lendity.com](https://lendity.com/growth/the-capital-stack-a-guide-not-to-accidentally-selling-your-entire-company-2812/) observes, every term on a term sheet has downstream consequences — model the cap table impact at three exit scenarios before signing.
Key Takeaways
- Match capital to risk layer: Senior debt funds collateralizable cash flows; mezzanine funds the acquisition gap; preferred equity funds where debt capacity is exhausted. Each layer has a structural role — do not conflate them.
- PIK interest preserves integration-phase cash flow: Negotiating a PIK toggle on mezzanine debt in years one and two meaningfully reduces cash debt service during the period of highest operational risk.
- Incurrence vs. maintenance covenants are not equivalent: Mezzanine and preferred instruments typically carry incurrence-based covenants. Senior facilities use maintenance covenants. Understand the distinction before stacking both in the same deal.
- Equity kickers must be modeled, not ignored: A 3% warrant at a $15M post-money valuation has a very different value at a $60M exit than at a $20M exit. Always model warrant dilution across exit scenarios before agreeing to coverage levels.
- Competitive tension is a structural tool: Running a parallel process with four to six gap capital providers — not a single bilateral conversation — is the single most effective way to compress pricing and improve covenant terms.


