
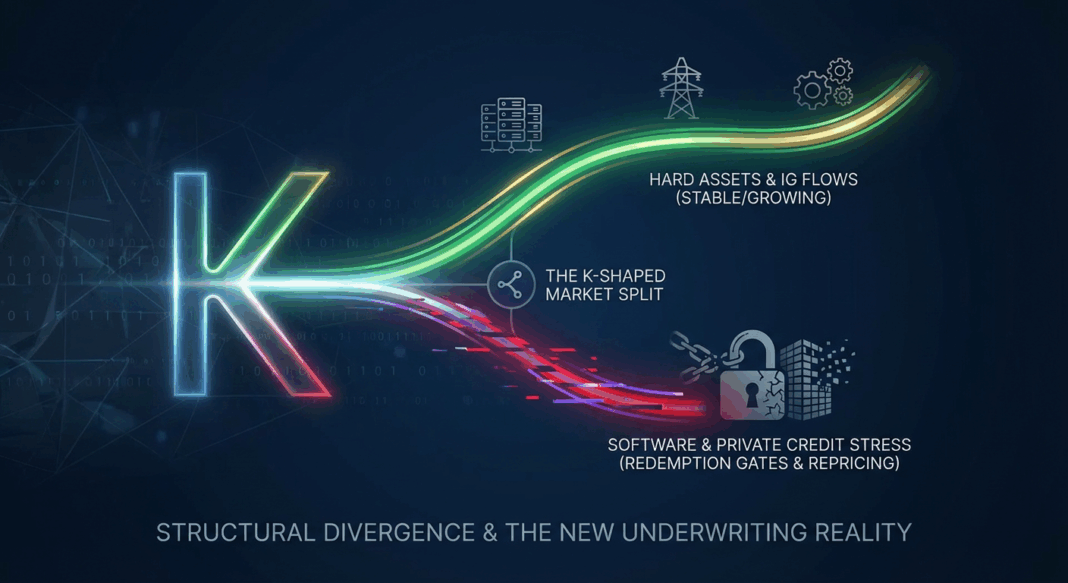
Macro Headline: A Credit Market Splitting in Two
The defining story of Q1 2026 is not a single data point — it is the structural divergence between two credit markets operating simultaneously inside the same economy. On one side, investment-grade bond bid-ask spreads are sitting near all-time lows, public corporate bond market depth and breadth are at post-GFC highs, and — as of April 15 — the high-yield spread had compressed to 285 basis points, placing it in the 5th historical percentile of all observations, according to finexus.net. On the other side, leveraged loan primary volumes have collapsed 34% year-over-year to just $235 billion in Q1 2026 — the slowest start since the 2020 pandemic — redemption gates are being triggered at some of the largest private credit vehicles in the market, and a record 9.2% private-credit default rate was reported for 2025 by Fitch, per atlaspeakresearch.com.
This is the K-shaped credit cycle in its most acute form. The macro trigger is a convergence of geopolitical stress, the March 2026 oil shock sending Brent crude above $120 per barrel, a Federal Reserve that paused its rate-cutting cycle in response, aggressive 2025-era trade tariffs, and AI-driven disruption compressing the enterprise value of software-heavy leveraged loan portfolios. The result is a market where Oracle can price $38 billion in AI infrastructure debt with ease, while companies rated B- or below are being systematically locked out of refinancing windows, according to investor.wedbush.com.
Quantitative Market Snapshot
The data box below synthesizes current public and private credit metrics against prior-period benchmarks. Operators and investors should treat these KPI thresholds as the new baseline for underwriting conversations.
| Metric | Current Value | Prior Period | Change | Source |
|---|---|---|---|---|
| High Yield Spread (ICE) | 285 bps (Apr 15, 2026) | 328 bps (Apr 2, 2026) | ‑43 bps (1 month) | finexus.net |
| Investment Grade Spread | 80 bps (Apr 15, 2026) | 92 bps (1 month prior) | ‑12 bps (1 month) | finexus.net |
| BB Spread (High Yield) | 173 bps | 202 bps (1 month prior) | ‑29 bps (1 month) | finexus.net |
| CCC Spread | 924 bps | 963 bps (1 month prior) | ‑39 bps (1 month) | finexus.net |
| Q1 2026 Leveraged Loan Volume | ~$235–$241B | $355B (Q1 2025) | ‑32–34% YoY | sikich.com / investor.wedbush.com |
| Private Credit Default Rate (Fitch) | 9.2% (FY 2025) | 8.1% (FY 2024) | +110 bps YoY | atlaspeakresearch.com |
| Distress Ratio (Loans <80 cents) | 7.23% (Mar 2026) | Below 5% (Q4 2025) | Highest in 3 years | investor.wedbush.com |
| Software Borrower Avg. Leverage | 7.4x EBITDA | 5.9x (broader loan pool) | +1.5x premium vs. market | atlaspeakresearch.com |
On the KPI benchmarking front, lender underwriting standards are tightening materially at the margin. The most active segment of the leveraged loan market saw spreads widen by approximately 100 basis points in February and March before partially recovering, reflecting elevated sensitivity to FCCR headroom and leverage multiples in software, media, and consumer discretionary credits. For borrowers, the operative message is clear: lenders are demanding tighter debt-to-EBITDA ratios and higher fixed charge coverage ratios than were acceptable even six months ago, particularly for any issuer rated below BB, per sikich.com.
Sector Analysis: Where Capital Is Flowing — and Where It Is Retreating
Software & SaaS: The Epicenter of Underwriting Repricing
Software has become the single most significant pressure point in the private credit and leveraged loan ecosystem. With approximately 16% of the $1.5 trillion U.S. loan market — roughly $235 billion — concentrated in software, and over 50% of those loans rated B- or below, the sector faces a compounding problem: AI-driven business model disruption is compressing enterprise values precisely as refinancing windows narrow. Software equity indices fell approximately 22% since January 2026, mechanically increasing loan-to-enterprise-value ratios on associated credits. Private credit software exposure is estimated at ~20% of AUM by BNP, and roughly 30% of software loans mature by 2028, per atlaspeakresearch.com. Lenders are actively repricing covenant packages, demanding higher FCCRs, and reducing advance rates on software-collateralized credit facilities.
AI Infrastructure, Energy & Hard Assets: The Upper Arm
In sharp contrast, AI infrastructure and energy-adjacent hard asset credits are attracting strong lender appetite. Oracle’s $38 billion debt package for AI data center expansion priced successfully in Q1 2026, and the energy sector — despite equity volatility — is outperforming on a YTD credit basis. Materials (+13.3% YTD) and Industrials (+10.4% YTD) are the two strongest equity sectors, signaling that real-asset and infrastructure-backed credit continues to command premium pricing and deep investor demand, per finexus.net.
Private Credit Structures: Liquidity Mismatch Stress
The structural crack in private credit is most visible in semi-liquid wealth-channel vehicles. Blackstone’s BCRED received $3.7 billion in redemption requests (~7.9% of NAV) in Q1 2026, requiring a $400 million sponsor capital injection and a gate expansion to 7%. BlackRock’s HLEND received requests equal to 9.3% of NAV with 19% of its portfolio in software. Cliffwater’s Corporate Lending Fund saw requests of approximately 14% of NAV, capping repurchases at 7%. Public BDCs are now trading at an average of 78 cents on the dollar of reported NAV, down from ~85 cents at the start of 2026, per atlaspeakresearch.com. This public-market discount is a critical signal: it represents the market’s assessment of mark-to-model valuation risk inside private credit books.
Healthcare & Media: Widening Divergence
Healthcare faces a dual headwind from 100% tariffs on certain branded pharmaceuticals and complex international supply chain exposure introduced under 2025 trade policy. Media has seen borrowers like Cumulus Media file for Chapter 11 for the second time in eight years. In both sectors, lenders are applying stricter FCCR minimums and lower leverage ceilings than in prior cycles, per investor.wedbush.com.
Operational & Strategic Implications
For Borrowers and Operators
The 90/10 rule now governs credit market access: the top 90% of the credit quality distribution retains viable refinancing paths, but the bottom 10% faces an existential liquidity crunch. Operators approaching debt walls in late 2026 or 2027 should model rescue financing at double-digit all-in rates and prepare for asset dispositions of non-core business units to reduce leverage multiples ahead of any refinancing process. Borrowers in software, media, or healthcare with leverage above 6.0x EBITDA and FCCR below 1.25x should treat the current window — where M&A-related financing for investment-grade quality credits remains available — as an asset to preserve rather than a given. For deals that do clear the market, concentration risk is extreme: more than 40% of Q1 2026 institutional loan volume came from just five mega-transactions, per sikich.com.
For Institutional Investors and Lenders
The public credit liquidity argument has been empirically resolved in favor of public markets. PIMCO’s analysis of TRACE data confirms that IG and HY bond market depth, breadth, and transaction costs are all at or near post-GFC bests, with bid-ask spreads close to all-time lows and turnover ratios rising materially even in off-the-run and small-issuer credits, per pimco.com. Against the backdrop of private credit redemption gates and NAV discounts, institutional allocators should pressure-test illiquidity premiums in private credit against the genuine liquidity improvements in public IG and HY markets. The payment-in-kind income share in BDC portfolios has increased materially since 2019, per FSOC data cited by atlaspeakresearch.com — a structural factor that can mask underlying credit deterioration in reported yield and NAV metrics.
Forward View: The Next 3–6 Months
Historical analysis of periods when high-yield spreads were within 10% of the current 285 bps level shows a median 3-month forward spread change of just +1 basis point, with a wide range of ‑46 to +44 bps, per finexus.net. The surface-level spread picture is therefore more stable than the underlying credit quality story. The key macro variables to monitor are Fed policy (a resumption of rate cuts would meaningfully relieve FCCR pressure on floating-rate borrowers), oil price trajectory (any sustained move below $100/barrel reduces the inflationary constraint on monetary easing), and the pace of software credit deterioration. If redemption pressures at semi-liquid private credit vehicles continue to compound, forced asset sales could pressure secondary loan prices, creating potential entry points for distressed and special-situations strategies. Private equity deal activity slowed meaningfully in Q1 2026, per sikich.com, which creates a headwind for sustained M&A-driven primary issuance in Q2 and Q3 — sustaining the selectivity dynamic that defines this market.
Key Market Insights
- The K-shape is structural, not cyclical. AI disruption of software valuations and tariff-driven supply chain stress are permanently repricing credit risk in two of the largest private credit sector concentrations — this is not a temporary spread widening event.
- Private credit’s retailization has met its first real stress test. Redemption gates at BCRED, HLEND, North Haven, and Cliffwater reveal that semi-liquid wealth-channel vehicles have a structural liquidity mismatch that sponsor capital injections and asset sales are papering over, not resolving.
- Public credit markets are outperforming on liquidity. PIMCO’s TRACE-based analysis confirms that IG and HY bond market depth, breadth, and transaction costs are at post-GFC bests — a direct counter-argument to the private credit illiquidity premium thesis.
- Software borrowers face a compounding refinancing crisis. With 7.4x average EBITDA leverage, 50% rated B- or below, 22% equity market declines, and a 2028 maturity wall, the sector’s refinancing math is deteriorating faster than reported NAVs reflect.
- Hard assets and AI infrastructure are the clear lender-appetite beneficiaries. Operators with real-asset collateral, infrastructure-linked cash flows, or AI-adjacent revenue streams are accessing capital at meaningfully tighter spreads and with fewer covenant concessions than the broader market.


